Introduction
If you are researching property investment or rental accommodation, you may have come across the term HMO. But what is a HMO property in practical terms? Put simply, HMO means House in Multiple Occupation. It generally describes a property where several people live as separate households while sharing facilities such as a kitchen or bathroom.
The concept sounds straightforward, but HMO arrangements can involve specific rules, licensing requirements, safety responsibilities, and tenancy considerations. These requirements can also vary depending on the location and the type of property.
For landlords, understanding what is a HMO property is important before converting or renting a home to multiple occupants. For tenants, knowing how an HMO works can help clarify rights, responsibilities, and living arrangements.
This guide explains the concept in plain language and uses realistic examples to show how different HMO arrangements can work.
What Is a HMO Property?
A HMO property is typically a residential property occupied by people who are not all members of the same household and who share certain facilities.
A common example is a house rented to five unrelated professionals. Each person may have a private bedroom, while the tenants share a kitchen and bathrooms. Depending on the applicable legal definition, this type of property may qualify as an HMO.

The important point is that what is a HMO property cannot always be determined simply by counting bedrooms. The legal definition can depend on factors such as the number of occupants, the number of households, the relationship between residents, and how the accommodation is used.
For that reason, landlords should check the rules applying to their particular property rather than assuming that every shared house is automatically subject to identical requirements.
How Does an HMO Property Work?
An HMO is designed around shared residential accommodation.
Imagine a five-bedroom house. Each bedroom is occupied by an unrelated tenant. The tenants have individual agreements for their rooms but share the kitchen and two bathrooms.
In everyday terms, this is a typical HMO arrangement.
The landlord generally remains responsible for the property itself and may have additional obligations concerning maintenance, fire safety, facilities, and other standards. Tenants are normally responsible for keeping their own rooms and shared areas reasonably clean and following the terms of their agreements.
The exact legal responsibilities depend on the jurisdiction, tenancy structure, and licensing requirements.
Private Rooms and Shared Facilities
Many HMOs have private bedrooms combined with shared kitchens, bathrooms, dining areas, or living rooms.
Some properties may have ensuite bedrooms, reducing the number of facilities residents share. However, having an ensuite does not automatically mean a property cannot fall within an HMO definition.
Separate Households
The concept of separate households is particularly important.
A family living together in a normal family home is generally treated differently from several unrelated individuals renting rooms in the same property. Couples and certain groups living together may also be treated differently under local legislation.
Therefore, understanding the household structure is essential when determining whether a property qualifies as an HMO.
Real Example: A Five-Bedroom Shared House
Consider a five-bedroom property in a busy urban area.
The landlord rents one bedroom to each of five unrelated workers. Everyone has their own bedroom. The kitchen, lounge, and bathrooms are shared.
The tenants have different work schedules and may not know each other before moving in. The landlord manages the property and collects rent from each occupant.
This is a straightforward example of the type of arrangement commonly associated with an HMO.
Before operating the property, the landlord should determine whether an HMO licence is required and whether the property meets applicable housing, safety, occupancy, and management standards.
Real Example: Three Friends Sharing a Home
Now consider three university friends renting an entire house together under one tenancy agreement.
They share the kitchen and bathroom, but they also form a group living together by agreement rather than simply renting individual rooms from a landlord.
Whether this arrangement qualifies as an HMO depends on the applicable legal definition and local rules.
This example demonstrates why asking what is a HMO property requires more than looking at the number of people living in a building.
The tenancy structure and relationship between occupants can matter just as much.
Real Example: A Property With Ensuite Bedrooms
Suppose a landlord owns a six-bedroom house. Each bedroom has a private ensuite bathroom, but all occupants share a large kitchen.
The tenants are unrelated individuals who rent their rooms separately.
The presence of ensuite bathrooms does not necessarily remove the property from HMO rules. The relevant authorities may still consider the number of occupants, households, facilities, and use of the property.
Landlords should therefore avoid relying on assumptions such as “everyone has their own bathroom, so it is not an HMO.”
Why Do Landlords Choose HMO Properties?
HMO properties can be attractive to some landlords because rental income is often generated from several occupants rather than one household.
For example, instead of renting an entire five-bedroom property to one family, a landlord may rent individual rooms to five tenants.
However, potentially higher gross rental income can come with additional responsibilities and costs.
The property may require more frequent maintenance because more people use the facilities. Utilities may also be included in the rent, depending on the agreement. Management can become more demanding because the landlord is dealing with several occupants rather than one household.
Therefore, an HMO investment should be evaluated using the complete financial picture rather than rent alone.
HMO Licensing and Legal Requirements
One of the most important considerations is licensing.
Certain HMOs require a licence under applicable housing legislation. The criteria can depend on the number of occupants, the number of households, the property structure, and local authority rules.
Additional licensing schemes may also apply in some areas.
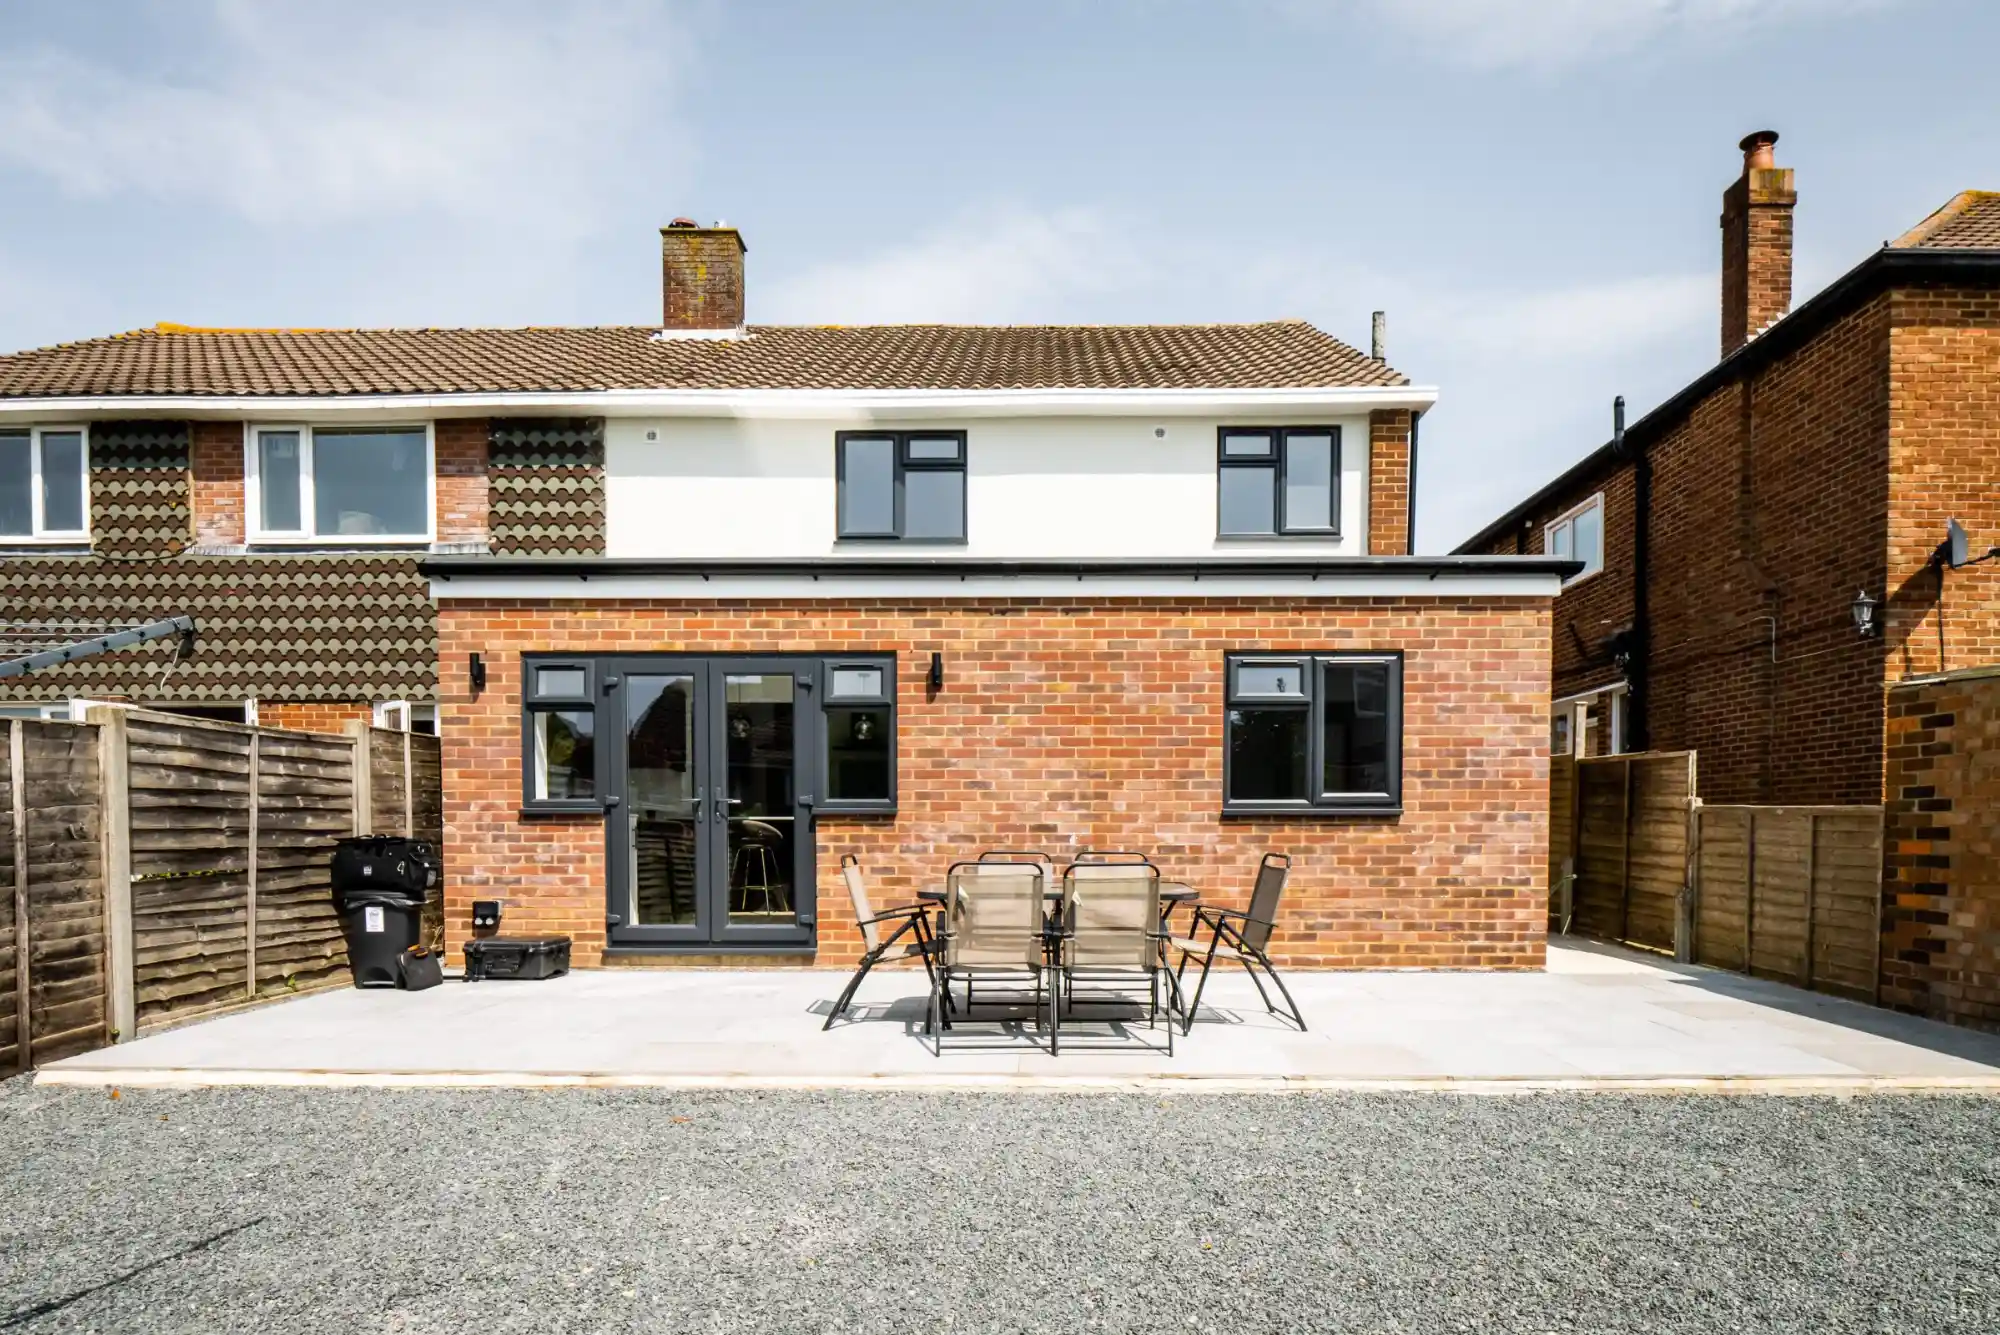
A landlord who is planning to convert an ordinary home into shared accommodation should check the relevant local authority requirements before making changes or signing multiple tenancy agreements.
Fire and Safety Standards
Fire safety is a major consideration in shared accommodation.
An HMO may have several people sleeping in different rooms, which can create additional evacuation and management considerations. Requirements may cover alarms, escape routes, fire doors, emergency arrangements, electrical safety, and other measures.
The exact requirements depend on the jurisdiction and property.
Property Conditions
Shared properties need to provide suitable living conditions.
Bathrooms, kitchens, heating, ventilation, lighting, electrical systems, and other facilities may need to meet specific standards. Overcrowding rules can also affect how many people can legally occupy particular rooms or properties.
A landlord should verify the applicable standards before operating an HMO.
HMO Property Management Is Different
Managing an HMO is often more involved than managing a conventional single-household rental.
With several tenants, small issues can become more complicated. For example, one tenant may report a plumbing problem while another complains about cleaning in a communal area.
The landlord needs a practical system for maintenance, communication, inspections, and repairs.
Clear tenancy agreements are particularly useful because they explain matters such as rent, deposits, utilities, access, cleaning responsibilities, and house rules.
Good management can also reduce disputes because tenants understand what is expected from everyone living in the property.
HMO Property vs. Ordinary Rental Property
The difference becomes clearer through a simple comparison.
A conventional rental might involve one family renting an entire three-bedroom house. The family shares the home as one household and deals with the landlord under a single rental arrangement.
An HMO might involve three or more unrelated individuals occupying rooms in a property while sharing facilities.
The distinction is not merely about the number of bedrooms. Legal definitions determine whether particular arrangements fall within HMO legislation.
This is why landlords should check the relevant rules before deciding how to structure a rental property.
What Are the Advantages and Challenges of an HMO?
The financial model can be one reason investors consider HMOs. Renting several rooms can potentially produce a different income profile from renting an entire property to one household.
There can also be consistent demand for shared accommodation in areas with universities, hospitals, business districts, and large employment centres.
However, HMOs can require more active management.
Higher tenant turnover may increase administrative work. Shared facilities can experience greater wear and tear. Utility costs may need careful budgeting. Licensing and compliance requirements can add expense.
The property also needs to be suitable for shared occupation. A building that works perfectly for one household may not work well for several unrelated tenants.
Legal Advice Can Be Important
Property law can become complicated when an owner is dealing with licensing, tenancy agreements, disputes, possession, rent, or regulatory requirements.
If you are unsure about a legal issue involving a property, consulting a qualified Lawyer in Dubai can help you understand the relevant legal position.
For broader information about rental arrangements, tenancy matters, and property-related legal issues, you can also explore Property & Rental Law.
Legal advice is particularly useful when a landlord is planning a substantial property conversion or facing a dispute with occupants.
How to Decide Whether a Property Could Be an HMO
The first step is to examine how the property will actually be occupied.
Ask who will live there, whether the occupants form separate households, whether rooms are rented individually, and which facilities they will share.
Next, check the applicable licensing rules. Do not assume that a property is exempt simply because it has fewer bedrooms than another HMO.
Finally, consider whether the building is physically appropriate for shared occupation. Room sizes, bathrooms, kitchens, fire safety, access, and general maintenance all matter.
Taking these steps before renting the property can prevent expensive compliance problems later.
Common Misunderstandings About HMO Properties
One common misunderstanding is that every shared house is automatically an HMO. In reality, legal definitions can depend on several factors.
Another misconception is that an HMO must always have individual bedrooms rented separately. Some arrangements can fall within relevant definitions even when the setup looks different.
It is also incorrect to assume that HMO rules are identical everywhere. Local authorities and different jurisdictions can have their own requirements.
The safest approach is to examine the specific property, occupants, tenancy arrangements, and applicable legislation.
Understanding What Is a HMO Property
Understanding what is a HMO property is essential for anyone considering shared residential accommodation. An HMO commonly involves several people from separate households living in the same property and sharing facilities, although the exact legal definition depends on the applicable rules.
The real examples show why the details matter. Five unrelated workers renting separate bedrooms is different from three friends renting a whole house together. A property with ensuite rooms can still potentially fall within HMO requirements.
For landlords, the key is to investigate licensing, safety, property standards, tenancy arrangements, and management responsibilities before proceeding.
Finding reliable legal guidance in the UAE can make complex matters easier to understand. TopLawyer provides useful information and professional resources covering areas such as property, business, family, and other legal topics. For readers seeking trusted legal insights and assistance, visit TopLawyer to explore helpful resources and connect with suitable legal professionals.
FAQs
What does HMO stand for in property?
HMO stands for House in Multiple Occupation. It generally refers to residential accommodation occupied by multiple people who are not all part of the same household and who share certain facilities.
What is a HMO property used for?
A HMO property is commonly used as shared residential accommodation. Individual occupants may rent bedrooms while sharing facilities such as kitchens, bathrooms, or communal areas.
How many people make a property an HMO?
The number varies according to the applicable legal definition. In many UK contexts, the definition considers multiple occupants from more than one household, but specific licensing thresholds can differ. Always check the rules applying to the particular property and location.
Do HMO tenants have their own rooms?
Often, yes. Many HMOs provide private bedrooms with shared kitchens and bathrooms. Some may also offer ensuite rooms.
Does an HMO need a licence?
Some HMOs require licensing, while others may be subject to different or additional local requirements. Whether a licence is needed depends on factors such as occupancy, property type, and location.
Is an HMO more profitable than a normal rental?
An HMO can generate rental income from several occupants, but it can also involve higher management, maintenance, utility, furnishing, and compliance costs. Profitability depends on the property’s purchase price, operating costs, occupancy, rent levels, and local market conditions.
Can a family house become an HMO?
Yes, a property originally designed as a family home can potentially become an HMO if it is converted or occupied as shared accommodation that meets the relevant legal definition.
Related Reading: How to Buy Property with Delinquent Taxes: Explained with Real Examples
Related Reading: Is buying rental property a good investment: Explained with Real Examples — full guide
Related Reading: Can foreigners Buy Property in Istanbul: Explained with Real Examples